On 7 October 2026 the Reserve Bank of India raised the repo rate for the first time in this cycle, and since then the most common question we hear at our Mulund West office is simple: "Should I still buy now, or wait?" If you are planning a home in Mulund, Vikhroli or anywhere in Mumbai's eastern suburbs, this FAQ explains what actually changed, how much it can move your EMI, and how to decide calmly.
According to the RBI's Monetary Policy Committee resolution of 7 October 2026, the policy repo rate was increased by 25 basis points, from 5.25% to 5.50%. The MPC also changed its stance to "calibrated tightening", which, in the RBI's own words, signals that rate cuts are off the table in the near term and the next move can only be a pause or another hike. The next MPC meeting is scheduled for 2 to 4 December 2026.
Most new floating-rate home loans from banks are linked to an external benchmark, usually the repo rate. Your interest rate is the repo rate plus a "spread" decided by the bank based on your credit score, income type and loan amount. When the repo rate goes up, the benchmark goes up, and so does your rate, while the spread usually stays the same.
Not always. Banks reset repo-linked loans on a schedule set out in your loan agreement, often once a quarter. Many banks also increase the tenure by default instead of the EMI. If you prefer to keep the tenure unchanged, you can usually request a higher EMI. Older MCLR-linked loans react more slowly. Check your sanction letter or ask your bank which option applies to you.
Rates differ by lender and profile, so always check the bank's own rate page. A few published examples after the hike:
Notice the pattern: your credit score can matter as much as the RBI decision. On Bank of Maharashtra's published table, the gap between the top and bottom score bands is more than two percentage points.
Here is an illustrative calculation using the standard EMI formula (not a bank quote). Take a 1 BHK at Rs 78.50 lakh all-inclusive and a loan of 80%, which is about Rs 62.8 lakh, over 20 years:
That is a difference of under Rs 1,000 a month. It is real money, but for most salaried families it is not the deciding factor. The bigger swings come from the price you negotiate, the spread you qualify for and the tenure you choose.
Nobody can promise where rates will go, and we would be wary of anyone who does. The RBI has openly said cuts are unlikely soon. Waiting therefore means betting on an uncertain future rate while paying rent in the meantime. A practical approach:
you have found the right home, your EMI stays comfortably within your monthly budget even if rates rise a little more, and you have your down payment plus stamp duty and registration costs ready.
the EMI only works at today's lowest advertised rate, your emergency fund would be emptied by the purchase, or you are still unsure about the location.
Remember that floating rates move both ways. If rates fall later, a repo-linked loan will pass that on, and you can also ask your bank to reprice or consider a balance transfer.
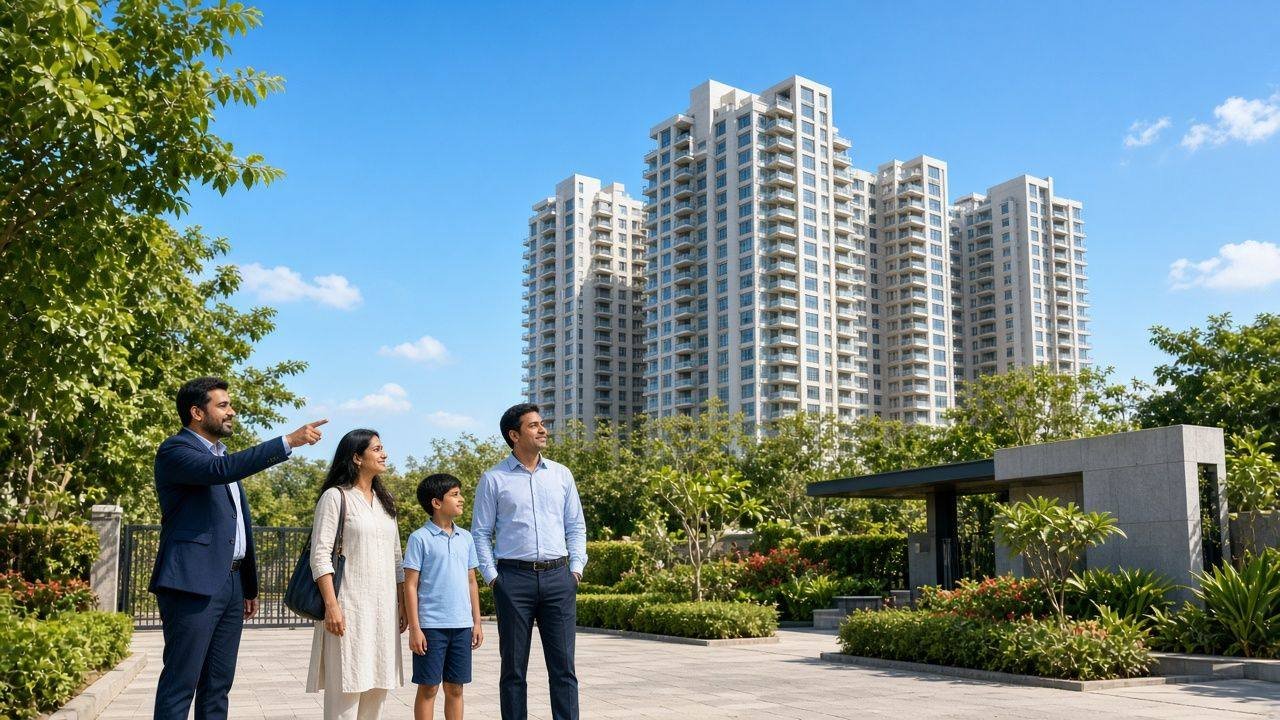
Yes. OM GN Willows at Kannamwar Nagar-1, Vikhroli East (MahaRERA P51800077593) offers 1 and 2 BHK homes starting from Rs 78.50 lakh all-inclusive. For buyers worried about EMIs, an all-inclusive price makes the loan amount far easier to plan. You can also browse ready and resale options on our properties page.
Before paying any booking amount, search the project's registration number on the official MahaRERA portal and confirm the registration is active, the promoter's name matches your agreement and the completion date is realistic. Stamp duty can be checked and paid through the IGR Maharashtra portal.
5.50%, after the 25 basis point increase announced on 7 October 2026.
Not during the fixed period. Fixed rates are usually higher to begin with and may convert to floating after a set term, so read the terms carefully.
Yes. You can ask your current bank to reduce your spread, usually for a small fee, or transfer the balance to another lender.
Yes. As a MahaRERA-registered agent (A51800006506), we help with buying, selling and renting, plus stamp duty and registration, from our Mulund West office.
Thinking about buying in Mulund or Vikhroli this season? Call or WhatsApp us on +91 90821 79935 or +91 93239 85063, visit gitarealestate.com, or send us a message. We will help you compare options honestly, without pressure.